
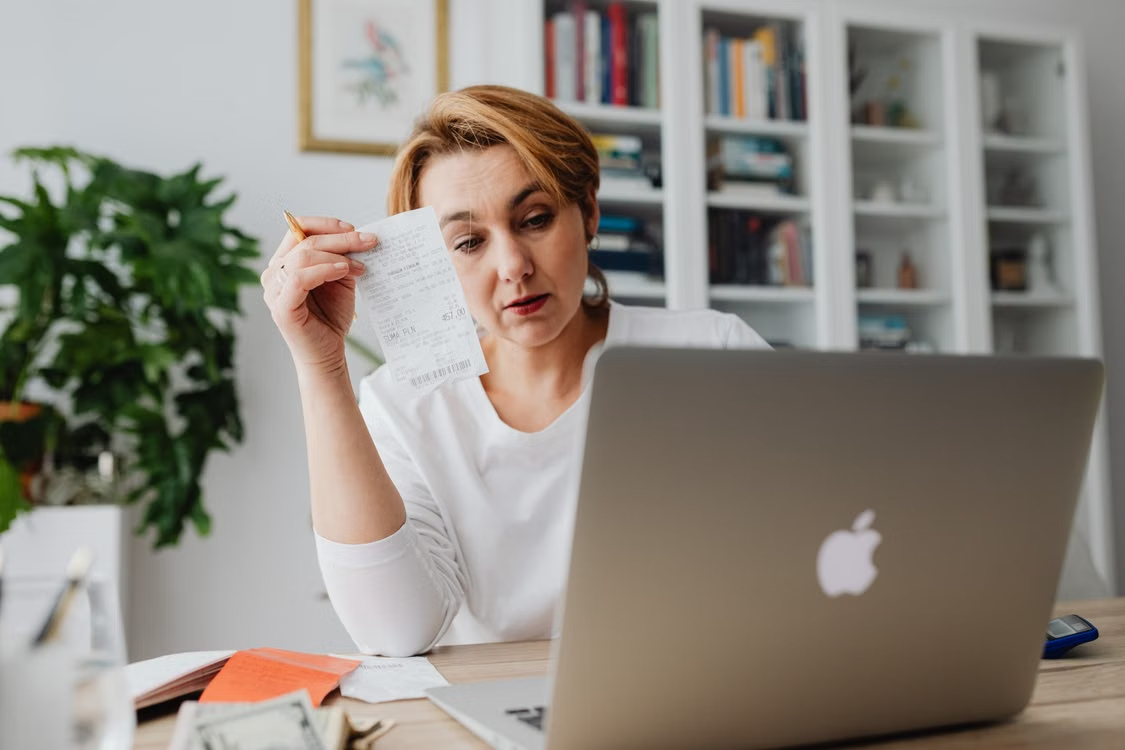
A sudden loss of income can turn ordinary household bills into urgent problems within days. Medical leave, an accident, or a delayed legal settlement may leave you trying to cover housing and groceries with far less money than usual. A clear crisis budget helps you protect basic needs while you explore temporary sources of support. Start with the bills that affect daily stability, then contact providers before due dates pass.
Prioritize Immediate Living Costs
List the expenses required to keep your household safe and functioning for the next 30 days. Housing, food, essential medication, transportation, and basic insurance usually belong at the top. The National Low Income Housing Coalition reports that short-term financial assistance can improve housing stability, which shows why rent or mortgage payments deserve early attention.
Next, build a survival budget with only income you know will arrive. If you have $2,000 available and essential costs total $1,850, pause subscriptions and optional purchases immediately. Keep the remaining $150 available for unexpected transportation, medication, or food costs. Don’t assign expected insurance payments or settlement proceeds until the money reaches your account.
How Lawsuit Loans Bridge Income Gaps
An injured plaintiff may spend months waiting for a personal injury case to settle while regular bills continue. In this situation, pre-settlement funding may provide an advance based on the pending claim. Some plaintiffs explore lawsuit loans to help cover immediate expenses while their case is ongoing. Before accepting an advance, review the fees, repayment terms, and projected settlement deductions with your attorney.
This type of non-recourse funding can help cover immediate living expenses, but it carries costs that reduce the amount eventually received from a settlement. Ask for the total repayment estimate in writing, including fees and how charges grow over time. Your attorney can confirm whether funding is permitted, explain how repayment would affect your expected recovery, and provide documents the funding company needs to review the claim.
Negotiate Pause Terms With Creditors
Call creditors as soon as you realize a payment may be late. Many lenders, medical offices, and service providers have hardship options, but assistance is often easier to arrange before an account becomes seriously overdue. Explain how long you expect the disruption to last and offer a payment amount you can realistically maintain. If you need more ideas for handling a financial crisis, review ways to set priorities, reduce expenses, and find additional support.
Ask specific questions during each call. Find out whether the creditor can move the due date, waive a late fee, reduce the minimum payment, or offer a short forbearance period. Confirm whether interest will continue and how the arrangement will appear on your credit report. Record the representative’s name, the date, and any confirmation number. Request written terms before sending money, since a verbal promise may not fully describe fees or future payment obligations.
Streamline Monthly Utility Commitments
Review electricity, water, phone, internet, and insurance bills for savings that won’t disrupt essential services. A mobile plan with unused data or an internet package with premium features may offer an immediate place to cut. Ask providers about lower-cost plans, hardship programs, and extended payment arrangements before canceling anything you rely on for work, school, or medical communication.
Small household changes can also stretch limited funds. Adjust the thermostat a few degrees, run full laundry loads, and unplug devices that draw power while idle. Set calendar reminders for revised due dates so a negotiated extension doesn’t become a missed payment. Once the crisis eases, restore paused services one at a time. Keeping a written record of every reduction and agreement will show exactly how much room remains in next month’s budget.

Comments are closed.